TRANSFER PRICING: DOES YOUR COMPANY NEED A TP STUDY REPORT?
If your company deals with a foreign parent, subsidiary or other related party, the transfer pricing rules probably apply. Here is what they ask for.
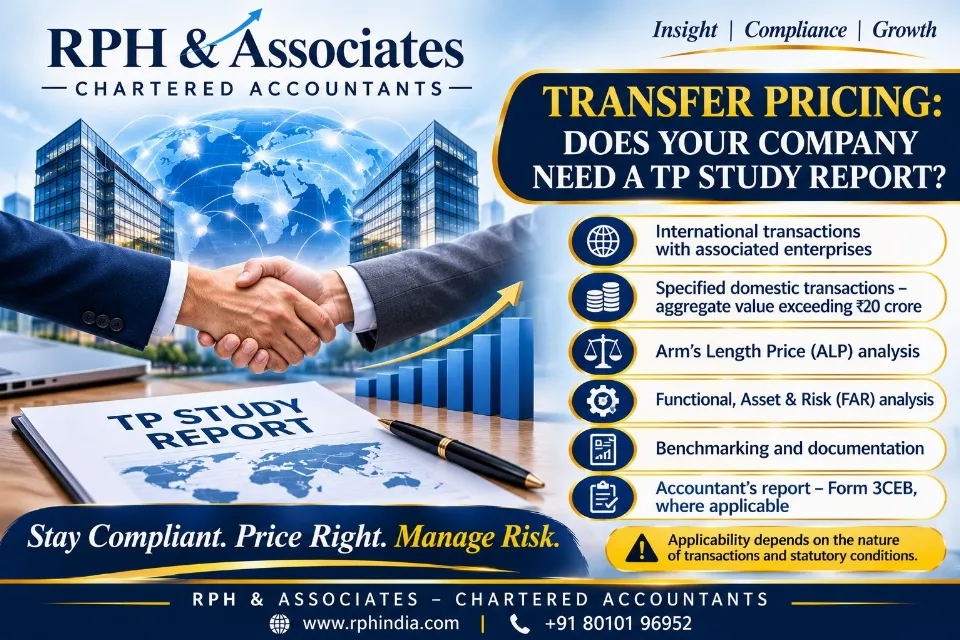
In India, transfer pricing provisions apply to international transactions between Associated Enterprises (AEs), transactions involving Notified Jurisdictional Areas, and certain specified domestic transactions (SDTs).
What is required?
1. Transfer Pricing Documentation
Businesses covered by the provisions must maintain prescribed records supporting how related-party transaction prices were determined. A comprehensive Transfer Pricing Study Report generally covers:
Identification of Associated Enterprises and related transactions.
Functional, Asset and Risk (FAR) analysis.
Selection of the Most Appropriate Method (MAM).
Benchmarking and comparable company analysis.
Determination and justification of the Arm's Length Price.
The detailed documentation requirements and applicable exemptions must be examined under the prescribed rules.
2. Accountant's Report – Form 3CEB
A person entering into an international transaction or specified domestic transaction is required to obtain and furnish the prescribed accountant's report in Form 3CEB by the statutory specified date.
3. Master File and Country-by-Country Reporting
Larger multinational groups may also have separate compliance obligations relating to Master File and Country-by-Country Reporting (CbCR), depending on prescribed group revenue and transaction thresholds.
Why does it matter?
Transfer pricing adjustments can result in significant tax demands, interest and penalties. Inadequate documentation or incorrect reporting can increase the risk of disputes during income-tax assessments.
A properly prepared and contemporaneous Transfer Pricing Study Report helps demonstrate the commercial rationale and arm's length nature of related-party transactions and provides important support during tax assessments.
Does your company need a TP Study?
You should consider a transfer pricing review if your company:
Imports or exports goods or services from foreign group companies.
Pays or receives management, consultancy or technical service fees.
Enters into inter-company loans, guarantees or royalty arrangements.
Undertakes transactions with associated enterprises.
Has specified domestic transactions covered by the statutory provisions.
Don't wait for an income-tax notice. Review your transfer pricing exposure proactively.
Our Transfer Pricing Services
RPH & Associates provides professional assistance in:
Transfer Pricing Applicability Review
Transfer Pricing Study Reports
FAR Analysis and Benchmarking
Arm's Length Price Determination
Form 3CEB Certification and Compliance
Master File and Country-by-Country Reporting
Transfer Pricing Assessment and Advisory Support
Connect with us for a Transfer Pricing Compliance Review.