Corporate Financial Reporting: Navigating Contemporary Standards and Structural Evolution
Corporate financial reporting, Ind AS adoption, regulatory developments, enhanced disclosures and ESG reporting. Explore how RPH & Associates helps businesses navigate evolving financial reporting requirements.
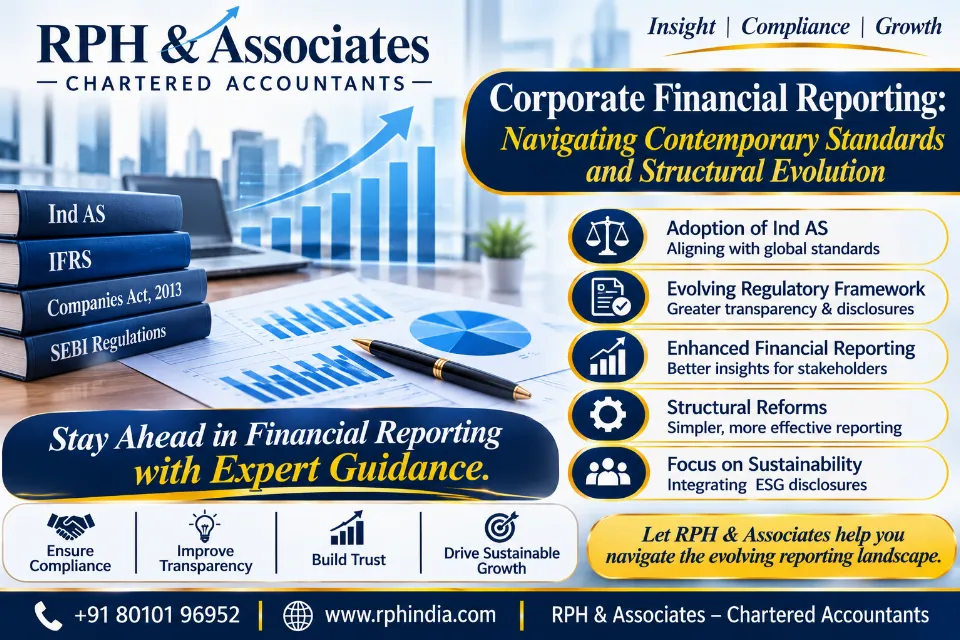
In an era of accelerated economic transformation, corporate financial statements have evolved from static compliance documents into dynamic instruments of strategic communication. For institutional stakeholders, creditors, and market analysts, interpreting these reports requires a nuanced understanding of modern accounting frameworks, subtle structural shifts, and the underlying economic reality they endeavor to capture.
1. The Triad of Core Financial StatementsModern corporate reporting relies on an interconnected triad of statements that, when read in tandem, provide a holistic view of enterprise performance and financial position:
· The Statement of Financial Position (Balance Sheet): Moving beyond historical cost paradigms, this snapshot reflects the economic resources controlled by the entity (assets) and the claims against those resources (liabilities and equity) at a precise temporal juncture.
· The Statement of Profit or Loss (Income Statement): This tracks operational efficacy over a fiscal period, segregating core recurring profitability from anomalous or non-operating events to ascertain true earnings quality.
· The Statement of Cash Flows: Acting as a vital liquidity bridge, this statement disaggregates cash movements into operating, investing, and financing activities—stripping away the accrual-based accounting distortions inherent in the income statement.
· Statement of Changes in Equity: Provides a transparent reconciliation of share capital, retained earnings, and other comprehensive income (OCI), capturing unrealized gains and losses that bypass the standard income statement.
2. Contemporary Paradigm Shifts & Regulatory ChangesThe architecture of financial reporting is undergoing a profound metamorphosis, driven by global regulatory harmonization (such as IFRS, US GAAP, and Ind AS) alongside rapid technological integration:
Shift Toward Fair Value and Mark-to-Market Valuation
Traditional historical cost accounting is steadily ceding ground to fair value methodologies (IFRS 13). This transition demands that balance sheets reflect current market valuations—particularly for financial instruments, derivatives, and investment properties—thereby increasing economic relevance at the expense of short-term earnings volatility.
Overhaul of Lease Accounting and Revenue Recognition
Recent accounting reforms have fundamentally reshaped balance sheet optics. Under IFRS 16 / ASC 842, virtually all operating leases must now be recognized on the balance sheet as Right-of-Use (RoU) assets paired with corresponding lease liabilities, eliminating traditional off-balance-sheet financing. Simultaneously, IFRS 15 / ASC 606 introduced a rigorous five-step model governing when and how revenue is recognized, curbing premature top-line inflation.
The Rise of Integrated and ESG Disclosures
Financial statements are no longer evaluated in isolation from non-financial capital. With frameworks like the ISSB (IFRS S1 and S2) and India's BRSR (Business Responsibility and Sustainability Reporting), corporate reports increasingly integrate Environmental, Social, and Governance (ESG) metrics, recognizing that climate risk and sustainability directly impact long-term enterprise valuation.
Digitalization and XBRL Reporting
The widespread adoption of extensible Business Reporting Language (XBRL) has transformed static disclosures into structured, machine-readable datasets. This enables institutional analysts and regulators to parse footnotes, segment disclosures, and related-party transactions with algorithmic precision.
3. Critical Analytical Focal PointsWhen dissecting contemporary financial statements, sophisticated observers look past headline net income figures to evaluate deeper structural health:
1. Earnings Quality & Accrual Divergence: Comparing Net Income against Operating Cash Flow (CFO) to verify whether reported profits are backed by actual cash inflows or inflated by aggressive accounting estimates.
2. Working Capital Dynamics: Evaluating the conversion cycles of inventory, trade receivables, and payables to diagnose operational friction or concealed liquidity strains.
3. Contingent Liabilities & Footnote Disclosures: Scrutinizing off-balance-sheet commitments, pending litigations, and critical accounting judgments tucked within the Notes to Accounts.
4. ConclusionFinancial statements remain the foundational grammar of global commerce. As accounting standards continue to pivot toward transparency, fair value measurement, and sustainability-linked disclosures, the ability to read between the lines of these documents separates superficial observers from astute financial strategists.